A smartphone storage upgrade looks modest beside the investment required to build an AI data center. Yet when a major handset platform raises its starting capacity, the change can influence a substantial volume of NAND demand without requiring a comparable increase in phone shipments.
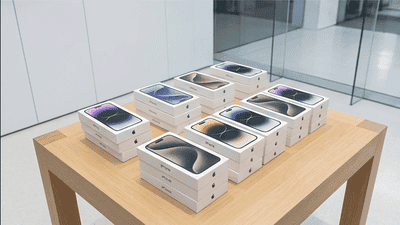
Apple’s iPhone 17 provides a clear example. Its starting storage increased to 256GB, double the 128GB starting point of the previous standard model. That is a confirmed product change, not a prediction that every iPhone generation will double its capacity. The important commercial question is how the higher minimum affects the average storage configuration buyers actually choose.
The central theme is content: more memory or storage inside each device can support semiconductor demand even when unit growth is limited. But the benefit depends on product mix, manufacturing economics, and the wider balance between mobile and enterprise applications.
A Higher Minimum Changes the Demand Floor
When a manufacturer removes a lower-capacity entry option, buyers who would have selected it move to a larger minimum. That raises the floor for storage content in the affected model.
The effect is different from adding an expensive top-end tier. A premium option increases demand only when customers choose it; a higher minimum changes every sale that would otherwise have used the discontinued capacity.
For a memory analyst, this makes base-capacity changes especially useful to track. They can alter the purchasing mix more predictably than headline maximum capacities.
However, the result still depends on which models sell. A higher minimum in one product does not establish the same increase across a manufacturer’s entire lineup or across the smartphone market.
Average Capacity Matters More Than the Headline
Total smartphone storage demand depends on device shipments and the average capacity installed per device. Both variables need to be measured on a consistent basis.
Doubling the entry configuration does not necessarily double the model’s average capacity. Some buyers already purchased 256GB or 512GB versions, while others may now find the larger base model sufficient.
This can reduce movement into higher tiers. The manufacturer raises the minimum while customers redistribute their purchases within the new range.
For investors, the useful calculation follows the actual sales mix. It separates the capacity added to entry-level purchases from any change in the proportion of higher-capacity models. Without that distinction, the NAND-demand benefit can be overstated.
A Simple Scenario Shows the Difference
Consider an illustrative model range with half its buyers choosing 128GB, 30% choosing 256GB, and 20% choosing 512GB. Its weighted average capacity would be 243.2GB.
If only the 128GB configuration moved to 256GB and the other shares remained unchanged, the average would increase to 307.2GB, or approximately 26%.
That is a substantial increase, but it is not 100%. The example describes hypothetical purchasing behavior, not Apple’s disclosed mix.
The lesson is practical: changes in minimum capacity should be converted into a weighted-average estimate before being applied to shipment forecasts. The assumptions deserve as much attention as the resulting growth rate.
Capacity Growth Can Offset Weak Unit Growth
A smartphone market with limited shipment growth can still increase its demand for NAND if average storage content rises.
Conversely, a capacity improvement can be offset by lower unit shipments or a weaker mix of premium products. The net result depends on both dimensions.
This is why memory demand should not be forecast solely from handset shipment totals. Devices are becoming different semiconductor purchasing baskets over time.
From a manufacturer’s perspective, the relevant question is how much qualified storage the production plan requires. From an investor’s perspective, it is whether content growth is sufficient to support shipments and earnings after accounting for price and cost changes.
Why Users Need More Local Storage
Photos, video, applications, downloaded media, and accumulated personal data all compete for space. A phone used for several years can build a larger storage requirement even if the owner’s daily behavior changes little.
Higher-capability applications add another source of demand. Some functions retain data or models locally rather than relying entirely on a remote service.
These needs vary by user. A person who streams most content and manages files carefully may use far less space than someone recording video or keeping extensive offline libraries.
For product planners, a higher starting capacity can reduce the likelihood that entry-level buyers encounter constraints. For NAND suppliers, that product decision creates demand before the user fills the additional space.
On-Device AI Adds a New Storage Consideration
AI features can require downloaded models and supporting files. That creates a storage requirement distinct from ordinary application code or personal media.
Apple’s technical information identifies approximately 7GB for its on-device intelligence models, while noting that overall available space varies with software, settings, and the model. The figure should not be treated as a universal AI requirement or as the sole reason for a capacity increase.
The broader implication is a larger set of demands on local storage. Manufacturers need room for operating systems, applications, user data, and selected computational resources.
For analysts, AI is therefore one contributor to the content trend—not a complete explanation of it.
Cloud Storage Does Not Replace the Physical Capacity
Cloud services can help users manage data, but they do not expand the NAND physically installed in the phone.
Some content can reside remotely, while applications, operating functions, and selected offline data still require local capacity. Network availability and user preferences influence the balance.
A larger local configuration can also coexist with cloud growth. Users may create more content, retain additional copies, or use services across multiple devices.
There is no fixed conversion between one additional gigabyte of handset storage and cloud infrastructure demand. For investors, the relationship needs to be evaluated through actual user activity and service architecture rather than inferred directly from a capacity specification.
NAND Storage and Mobile DRAM Must Stay Separate
Persistent storage and working memory perform different functions. Increasing a phone’s advertised storage capacity does not automatically increase its DRAM capacity by the same proportion.
Smartphones typically use low-power DRAM families appropriate to mobile power and packaging requirements. DDR5 server memory belongs to a different product context.
This distinction matters because a broad “memory upgrade” headline can blur several semiconductor markets. The iPhone storage bump directly concerns NAND-backed capacity, not a purchase of DDR5 modules.
For a supplier exposed to both DRAM and NAND, the same phone can contribute to multiple businesses. Those contributions should be analyzed separately, with attention to the actual component configuration.
The DDR5 Connection Runs Through the Server Ecosystem
DDR5 becomes relevant when the smartphone experience connects to cloud computing, online services, and data processing. Server platforms use working memory to support those activities.
But the relationship is indirect. More local smartphone storage does not establish a defined increase in DDR5 demand.
A larger handset capacity could support more content creation, while cloud architectures, software efficiency, and service usage determine the associated server requirements.
For an analyst, the useful approach is to distinguish direct device content from downstream infrastructure effects. Both can matter, but combining them without a clear causal basis risks double counting the same broad digital-growth narrative.
Enterprise Storage Shares the NAND Supply Chain
Mobile storage and enterprise SSDs serve different customers, but both draw on NAND manufacturing capability. Producers decide how to allocate output across qualified products and applications.
That creates a supply connection. Strong demand in one market can influence the commercial priorities of a manufacturer serving several others.
However, the products are not immediately interchangeable. Enterprise drives need controllers, firmware, validation, and performance characteristics that differ from handset storage.
A larger smartphone configuration can therefore add pressure to the broader NAND market without directly removing an equivalent quantity of finished enterprise SSDs. The effect depends on product allocation, technology, inventory, and manufacturing flexibility.
More Capacity Does Not Mean More Packages
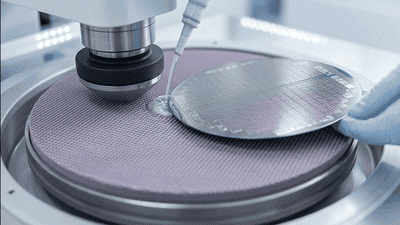
NAND density improvements can allow a manufacturer to place more storage within a similar physical footprint. A capacity increase does not necessarily require twice as many visible components.
The implementation depends on die capacity, package organization, architecture, and the product’s mechanical constraints.
This creates different implications for different suppliers. NAND bit demand can rise while package counts or assembly requirements change less dramatically.
For investors, the relevant unit must be clear. Bits, dies, packages, and finished devices are separate measures. A supplier selling one of them should not be assigned growth based automatically on another.
Manufacturing Economics Determine the Supplier Benefit
Higher storage content can support bit shipments, but revenue also depends on realized pricing. Profitability depends on manufacturing costs, yield, product mix, and investment requirements.
A producer can ship more bits while earning less per bit. Conversely, a favorable pricing environment can amplify the revenue effect of a modest capacity increase.
Technology transitions add another layer. Denser NAND can improve potential output, but its commercial advantage depends on stable yields and customer qualification.
From a financial analyst’s perspective, the capacity bump is a demand input rather than an earnings conclusion. The model still needs price, cost, and allocation assumptions.
Supplier Qualification Limits Immediate Substitution
A large smartphone platform needs storage products that meet its requirements for performance, power, reliability, and integration. Component selection therefore involves more than purchasing the lowest-priced available bits.
Qualification can create established supplier positions, but it does not guarantee permanent allocation. Customers can evaluate alternatives or change configurations over time.
The public capacity specification also does not identify the exact supplier mix in every device. That should not be inferred without reliable product-level evidence.
For investors, the appropriate question is which companies have demonstrated participation and how that participation translates into commercial volume. A product announcement alone cannot settle the answer.
Competitors Can Reinforce the Content Trend
A higher minimum from a prominent smartphone manufacturer can influence customer expectations. Competing brands may respond through capacity, pricing, or other product features.
That does not guarantee an immediate industry-wide increase. Manufacturers serve different price segments and face different cost constraints.
Some may raise storage in selected premium models while retaining lower capacities elsewhere. Others may emphasize promotional upgrades rather than permanently changing the minimum.
For NAND forecasting, the useful evidence is actual configuration adoption across shipment volumes. Competitive attention matters, but confirmed product mix determines the resulting demand.
Inventory and Launch Timing Complicate the Signal
Component purchasing can occur ahead of a product launch, while retail sales extend across subsequent periods. Supply-chain inventory therefore affects when the storage upgrade appears in supplier results.
Older models can remain available, and customers can choose discounted previous-generation devices. That moderates the immediate impact of a higher-capacity new model.
Channel stock also matters. Strong shipments into distribution do not necessarily establish the same pace of end-user purchases.
For analysts, the demand timeline needs to connect production plans, component purchases, finished-device shipments, and retail consumption. A capacity announcement is only one milestone in that sequence.
What to Monitor in the Upgrade Cycle
A useful dashboard separates direct demand from broader expectations.
- Track minimum and maximum capacities by model.
- Estimate the weighted-average configuration rather than the entry specification alone.
- Combine capacity trends with unit shipments and model mix.
- Follow NAND pricing, qualified supply, and customer inventory.
- Keep mobile DRAM separate from storage capacity.
- Assess enterprise-storage effects through allocation and actual deployment.
These measures provide a stronger foundation than assuming that a doubled minimum produces doubled memory demand.
The Upgrade Is Structural, but the Earnings Effect Is Conditional
A higher storage floor can permanently change the content of an affected smartphone model. That is a meaningful demand development even when handset volumes are not expanding rapidly.
The commercial result still depends on consumer choices, supplier participation, pricing, and manufacturing economics. DDR5 and enterprise storage connect to the story through the broader computing ecosystem, not through a direct one-for-one relationship.
The lasting signal is the movement toward more storage per device. For memory investors, the opportunity lies in translating that trend into a disciplined estimate of qualified bits, realized revenue, and sustainable profit.